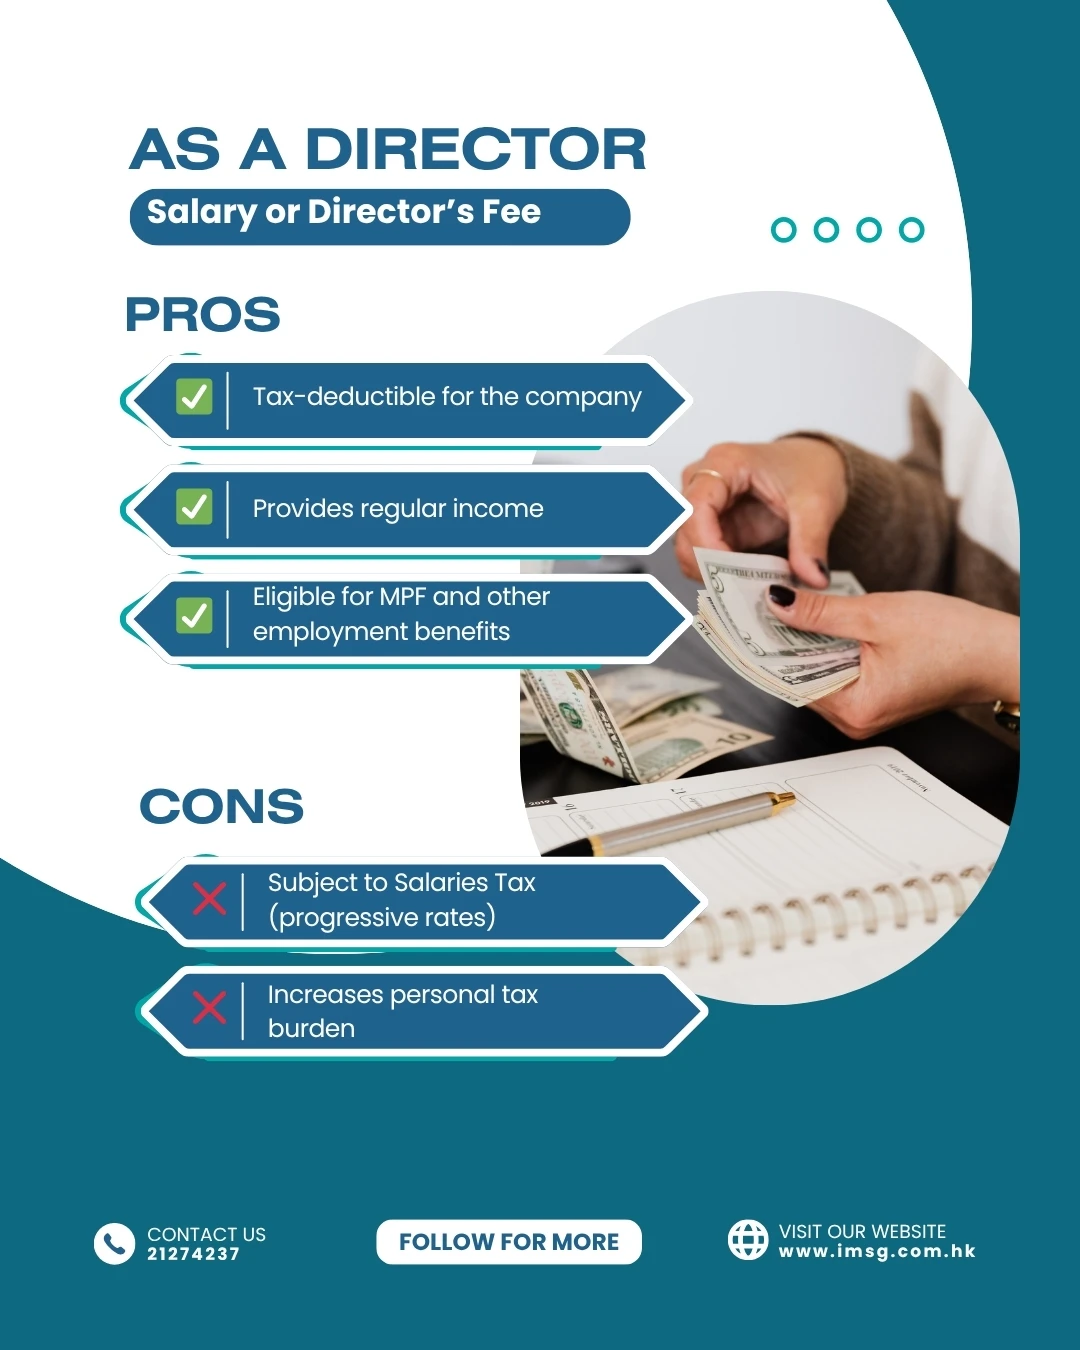
Salary, director’s fees and dividends have different legal, accounting and tax treatment. A payment should reflect its purpose, the company’s financial position and the approvals required.
Separate the two roles
A director manages the company and owes duties in that capacity. A shareholder holds rights under the shares and company documents. One person may occupy both roles, but a payment for work and a distribution of profit should be documented according to its actual purpose.
Salary and director's fees
Employment remuneration and director's fees may have different source and reporting questions. Keep the employment or service terms, authority for the payment, payroll or fee calculation and payment evidence.
A company deduction is not automatic merely because the recipient is a director or shareholder. The expenditure and the tax rules must support it. The individual's salaries-tax position and any obligations in their country of residence also require assessment. Relevant employer reporting, MPF and employment obligations should be checked separately.
Dividends
A dividend is a distribution, not interchangeable remuneration. It depends on the share rights, profits available for distribution and the required valid declaration or approval. Cash in the bank alone is not sufficient evidence that a dividend can lawfully be paid.
Keep the accounts and the directors' assessment, relevant resolutions and payment records. Shareholders do not have a general right to withdraw company cash whenever desired. Different share classes may carry different rights.
Cash, assets or an issue of shares can have different consequences and documentation. A pro-rata issue does not increase an existing holder's percentage ownership merely because the holder receives additional shares. Obtain advice before using a non-cash distribution or changing share rights.
Comparison for a private company
| Question | Salary or fees | Dividend |
|---|---|---|
| Purpose | Payment for employment or services | Distribution under shareholder rights |
| Evidence | Terms, approvals, calculation and payment | Available profits, share rights, valid declaration and payment |
| Company tax treatment | Deductibility requires assessment | A distribution is not treated as an ordinary salary deduction |
| Recipient position | Source, employment/director role and residence matter | Recipient type and relevant Hong Kong or overseas rules matter |
The absence of a general Hong Kong dividend withholding charge does not make every receipt tax-free in every jurisdiction. Corporate recipients may need an FSIE analysis for foreign-sourced income; personal and corporate recipients should not be conflated.
Before making a payment
Ask the accountant to review the proposed comparison against the current accounts and actual roles. Seek legal advice where distribution capacity, share rights or approvals are uncertain. Document the decision before payment and ensure the accounts and returns reflect it consistently.
See tax support and advisory and the IRD's profits tax information.